The life sciences industry has entered a new era of economic and geopolitical uncertainty. The drumbeat of stiff tariffs, evolving trade routes, and shifting supply chain priorities are forcing companies to rethink how they operate, source materials, and deliver products to market. For an industry that depends heavily on cross-border trade for both inputs and finished goods, these forces are creating unprecedented complexity.
At the same time, the pace of change is accelerating. A single trade restriction can send ripples through global supply networks, affecting where companies source parts, how they ship products, and how they reach the end user. For insurers underwriting life sciences risk, understanding these interconnected exposures has never been more important because economic pressures can fundamentally change how companies operate.
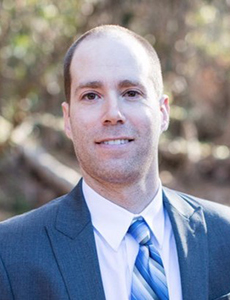
“We’re clearly in a new era for international trade, with the reality that trade is evolving and adding risk and uncertainty to the economy,” said Ben Wright, Head of The Hartford’s Global Insights Center.
“Trade routes are shifting from high tariff markets to low tariff markets. Supply chain priorities are changing as well.”

Ben Wright, Head of The Hartford’s Global Insights Center
For years, life sciences supply chains were optimized primarily for low cost. That priority is shifting quickly, according to Wright, as companies focus on building resiliency instead. The combination of tariffs, shifting trade routes, and reprioritized supply chains is adding cost, uncertainty, and risk across the economy — and the life sciences sector is particularly exposed.
“We have seen high tariffs placed on pharmaceuticals recently, with additional high tariffs planned for pharmaceuticals in the future,” Wright said.
“If that raises the cost for those pharmaceutical products, it raises questions about underwriting decisions.”
Another emerging issue is access to rare earth elements, which are critical to manufacturing certain equipment used throughout the life sciences supply chain. Because most rare earth production takes place internationally, any restriction on access could meaningfully change the risk profile for parts of the industry.
Wright believes companies should prepare for continued volatility.
“While we don’t know what the future holds, the one thing we can prepare for and expect is change.”

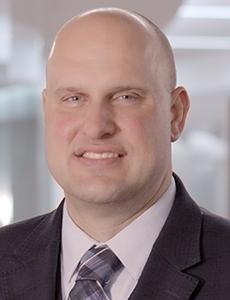
Brad John, Head of Life Science Industry Practice, The Hartford
The heightened complexity of the global operating environment is fundamentally changing how underwriters evaluate life sciences risk. According to Brad John, Head of Life Science Industry Practice at The Hartford, complexity and speed have become the two most significant forces shaping the risk landscape.
“Several years ago, underwriters certainly evaluated supplier concentration, contract manufacturing, and the supply chain,” John said.
“But what I think is different today is how interconnected those issues have become and how quickly the effects can spread. If you have one trade restriction change, it has a lot of downstream impact in terms of where companies are sourcing parts, where they’ve got to ship products to, and how they’re getting them to the end user.”
That interconnectedness has pushed underwriters to focus increasingly on organizational resilience and contingent exposures. Many life sciences companies do not own the facilities where their products are manufactured, tested, or sterilized, meaning they rely heavily on partners throughout the value chain.
Tariffs can begin as a cost or trade issue, but their effects can quickly move into operations, John noted, disrupting established processes and forcing companies to pivot to new suppliers or distributors.
“It becomes a question of how well they can recoup and how valid the controls are that they’ve had in place,” he said.
Geopolitical instability is also interrupting shipping lanes, energy supplies, and raw material sourcing. As the values of goods shift locations and follow different paths, exposures change with them.
“It’s prudent for not only the insured but also for the carrier to dive deep into these changes and ask the questions necessary to pinpoint what has shifted,” John said.
“This allows both parties to determine how the insurance program needs to change as a result.”
Emerging technologies like artificial intelligence are adding yet another layer to the risk equation. While A.I. can help companies stress-test scenarios and identify solutions more quickly, it also introduces potential risks around biased data or flawed thinking.
“A.I. can make flaws become apparent much more quickly and potentially exacerbate their impact as well,” John said. From an economic perspective, Wright noted that the use of A.I. is likely to shift the skills and job requirements needed for success in life sciences.
To help clients respond to this environment, The Hartford has invested in dedicated economic and geopolitical intelligence capabilities. Its Global Insights Center serves as the company’s internal think tank, conducting bespoke research that examines the insurance industry through an economic and geopolitical lens.
“Our role is to be a partner to the underwriters, providing them with the knowledge and intelligence they need to gain an edge in the marketplace,” Wright said.
That intelligence flows directly into underwriting conversations, helping underwriters understand how broader developments in trade, inflation, and interest rates might manifest in the operations of a specific insured.
For life sciences companies looking to strengthen resilience, John recommends several practical approaches: mapping critical dependencies, evaluating concentration risk and developing qualified alternatives to primary suppliers and partners.
“It’s okay to have a plan B, but you also have to make sure that plan B is as qualified as plan A, particularly in a highly regulated industry,” he said.
Companies should also proactively stress-test their continuity plans, an area where carriers can offer meaningful expertise. And as values and locations shift, the insurance program itself must evolve to reflect new exposures.
Wright emphasizes the importance of scenario planning.
“Prepare early, try to quantify risk as best you can, and build resiliency against different scenarios of future states of the economy,” he said.
“Doing that type of planning ahead of time can help you make decisions quickly when things change in real time.”
Looking ahead, geopolitical instability, manufacturing shifts, and financial impacts are likely to continue shaping the life sciences risk landscape. Flexibility, informed by strong economic and geopolitical intelligence, will be essential for companies and their insurance partners alike.
“In this new world of economic and geopolitical volatility, having access to economic and geopolitical intelligence and bespoke intelligence has now become a critical facet of doing business,” Wright said.
“It positions us well to provide economic and geopolitical insights to help our partners in the marketplace be more successful.”
To learn more, visit https://www.thehartford.com/business-insurance/midsize-life-science/life-science-solutions.
The information provided in these materials is intended to be general and advisory in nature. It shall not be considered legal advice. The Hartford does not warrant that the implementation of any view or recommendation contained herein will: (i) result in the elimination of any unsafe conditions at your business locations or with respect to your business operations; or (ii) be an appropriate legal or business practice. The Hartford assumes no responsibility for the control or correction of hazards or legal compliance with respect to your business practices, and the views and recommendations contained herein shall not constitute our undertaking, on your behalf or for the benefit of others, to determine or warrant that your business premises, locations or operations are safe or healthful, or are in compliance with any law, rule or regulation. Readers seeking to resolve specific safety, legal or business issues or concerns related to the information provided in these materials should consult their safety consultant, attorney or business advisors. All information and representations contained herein are as of October 2026.
The Hartford Insurance Group, Inc., (NYSE: HIG) operates through its subsidiaries, including the underwriting company Hartford Fire insurance Company, under the brand name, The Hartford®, and is headquartered in Hartford, CT. For additional details, please read The Hartford’s legal notice at www.thehartford.com.
![]()
This article was produced by the R&I Brand Studio, a unit of the advertising department of Risk & Insurance, in collaboration with The Hartford. The editorial staff of Risk & Insurance had no role in its preparation.