

 Newsletters
 Risk Central
 Digital Edition
The Future of Specialty Underwriting: John Russo of The Hartford on Data, Discipline and Trust
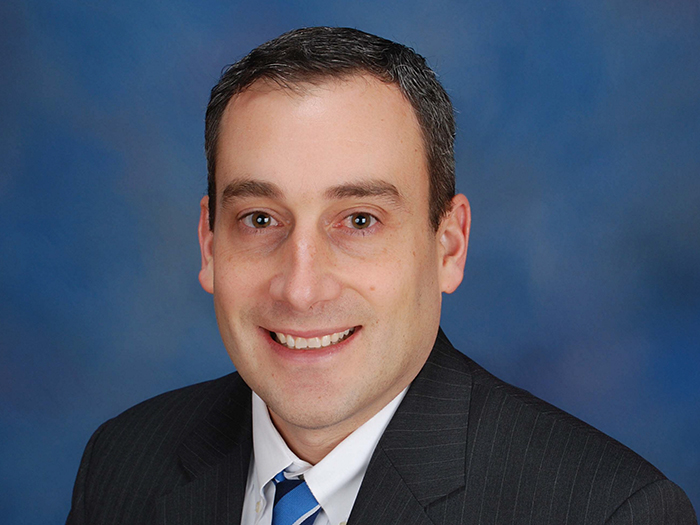
Risk & Insurance® editor in chief Dan Reynolds recently caught up with John Russo, Chief Underwriting Officer, Global Specialty, for The Hartford. What follows is a transcript of that discussion, edited for length and clarity.
Risk & Insurance: Thanks for meeting with us today, John. What experiences from your career will influence how you approach your role as lead underwriter for Global Specialty at The Hartford?
John Russo: I’ve had extensive experience across multiple divisions. I started and spent most of my career in small business, and I led a specialty part of small business for about six years. One of the most important lessons I’ve learned is that while making good individual risk decisions is critical, the aggregation of those decisions is even more important.
How you build your portfolio, how you structure it, how you go to market, and how you partner with your wholesalers — that aggregation and big-book view of risk is as important than the individual decisions themselves. I believe in maintaining a balanced book and partnering with all our wholesalers and specialty market producers. It’s about helping them understand what a balanced portfolio represents and then leaning into that vision together.
It’s a partnership that works both ways, but setting clear expectations for your book profile is one of the biggest learnings I’ve had over my career.
R&I: How challenging is it to communicate your desired book composition to the distribution network and ensure they understand your objectives?
JR: The challenge isn’t necessarily in how you communicate it. It’s understanding how the mix impacts profitability while balancing your partner’s need for solutions to solve problems for the customer.
At the end of the day, you have to understand both of those things — that your partners might need to solve individual challenges. And if you can meet your partner and solve those individual challenges, then the expectation is a balanced portfolio.
Balance can mean a lot of things. It could mean line, it could mean geography, it could mean an industry of business. But that portfolio balance you want is a two-way street between you and your broker partners.
R&I: What trends are shaping the specialty insurance markets, and how are they impacting the way underwriters evaluate complex risks?
JR: This is a time in the market cycle when having the right tools for an underwriter to understand exposure is extremely important. When I started my underwriting career, one of the biggest skills of an underwriter was finding data. Data is now being teed up to an underwriter better than it ever has been.
Finding data is no longer the skill set. There’s more data than any underwriter has ever had. It’s now actually how you use that data and how you use it to understand how you price a risk, how you set terms and conditions on a risk, the line size, the layer you have, and potentially excess casualty.
That access to data is one of the biggest changes we’ve had from an underwriting environment over the last 20 years, and especially the last year. In addition, how we bring science into that conversation has become increasingly important.
R&I: How has the underwriting role evolved in terms of data access and decision-making complexity?
JR: When I first started, underwriting had very limited access to data science, modeling, or any information outside of what was in the broker submission. Now they have that at their fingertips to be able to make decisions. Those models do not make the decision — the underwriters make the decision — but it’s how the underwriter actually brings that together and uses all this data to make a complex decision that is really the key to how an underwriter has to respond to it.
On a slight pivot, I’d say the litigation environment is another critical factor that an underwriter has to understand when pricing risk and determining what limits they want to put on risk. An underwriter also has to understand their jurisdiction, where they’re writing the risk, and how to set an appropriate price.
This means partnering with data and partnering with what they’re hearing in the market, with what their brokers are saying, and understanding what the competitive position needs to be on it — then taking all that to make a decision.
R&I: What is your approach to balancing underwriting discipline with the need to innovate?
JR:. It’s about having the right underwriting and being precise in this approach. It’s about being true to where you are from an underwriting standpoint, being true to the book you want to build, and understanding what’s in your market.
Underwriting discipline is being true to who you are from an underwriting standpoint and knowing the book you want to have.
It’s also about developing tools and solutions for the market that drive profitability while solving problems.
R&I: How should insurance companies approach their underwriting plans in a changing market environment?
JR: When you know your plan and stick to your plan, that doesn’t mean you don’t re-look at your plan quarterly or every year to assess whether something has changed. Trends change, litigation trends change, property performance changes, and models get updated with new catastrophe information.
Your plan is about creating a stable environment. Ideally, my underwriting philosophy is that if there is an area where we think we can make the right return on a risk and provide the right solution for a customer, we should be able to explore it. But then we need to understand how that fits into the portfolio we want to build.
R&I: With the advancement of technology and the volume of data available today, how can modern tools strengthen underwriting decisions while preserving the essential knowledge and expertise of underwriters?
JR: The real challenge is being able to harness all that data effectively. We now have access to models and data sources we haven’t seen before.
R&I: What does the evolved, modern underwriting experience look like for both underwriters and their broker-agent relationships?
JR: For underwriters and brokers, the sharing of data will continuously get better and easier than before. Even today, you still have applications fed in through email, hitting an underwriter’s desk, where they ultimately have to review the submission to see if this is something we want to underwrite.
In time, that’s going to be a more digital transaction than what you have today, where we’re sharing information back and forth on a submission much faster and easier. What we need from submissions is also going to change — the missing information process of back and forth and supplemental apps are going to become easier from a broker standpoint. All of that will be done through technology over time rather than the traditional way we’ve done it over the years.
Speed is going to matter more. There’s a ton of value in the underwriter-broker partnerships, and the first quote wins so many times. It’s up to us to give the underwriters the right tools and to synthesize the data so they can make that decision faster — so they can be the first accurate quote to their broker partner.
The broker can then solve a problem faster for the customer and provide certainty that they have a solution. Everything that I see in the future is enabling that faster, easier decision, and I think the expectation is going to be a faster, quicker decision for the broker and the customer. I mean, you don’t have to wait for information anymore — it’s right at your fingertips for everything that you do.
R&I: With the evolution of technology, email platforms, and the increasing need for speed in the insurance industry, is there a risk of losing the nuanced broker-underwriter dialogue that historically characterized deal-making?
JR: It’s a great question. The back-of-the-napkin deal probably still exists, although it’s far less common than it was before.
The real value of the underwriter relationship with the broker is about trust. It’s about when I send you something, you’re going to lean into it and you’re going to help me. Whether that’s enabled through technology or it’s fast, people still go to people they trust — not just people they like.
When underwriters trust their partners and their partners trust their underwriters, that deal still needs to get done. It might be enabled through technology, and there might be a few questions, but it’s still going to be that phone call.
R&I: What opportunities are you seeing in the Global Specialty business, either geographically or by economic sector?
JR: I believe in balance — it’s my most important principle. And I believe balance changes with market cycles, requiring adjustments over time. &