

 Newsletters
 Risk Central
 Digital Edition
Navigating Risk in Co-Living: How This Gallagher Broker Helped Build a Novel Insurance Model for Renters
There is a housing shortage of 4 to 7 million homes in the United States. From rising land and building material costs to strict zoning rules and stagnant wage increases, many are left in a tight spot where affordable housing is hard to come by.
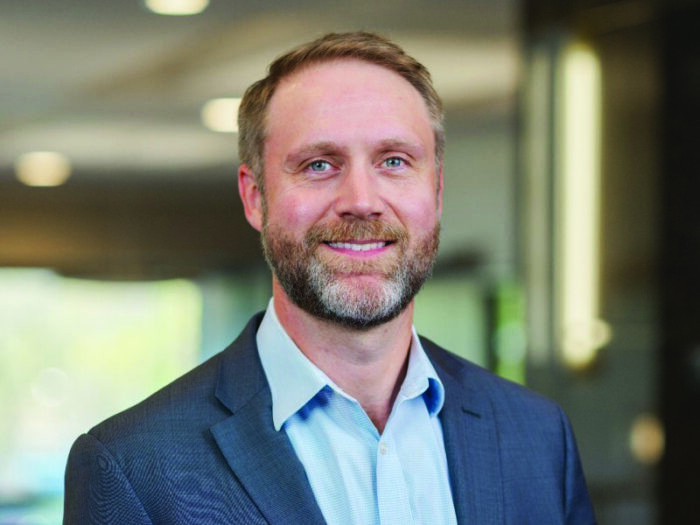
Luckily, with these high-level challenges, there are also organizations trying to work towards a viable and effective solution. For instance, Josh Clark, ACI, area vice president, Gallagher, works with a real estate technology client that’s already thinking ahead.
“They’re innovative in the way they’re helping create an option to directly impact the affordable housing crisis,” he said. The client is connecting residential property owners with renters through affordable co-living arrangements across the country, essentially giving low-income renters the opportunity to find a place to live without losing their entire savings in the process.
But in order to create a program to cover this endeavor, Clark and his team had to get creative.
Understanding Insurance, Inside and Out
When introduced to a new challenge, Clark said he leverages his background to help get clients the support they need. He started his insurance career in E&S on the underwriting side, moving into loss control as a boots-on-the-ground risk manager and overseeing activities for 36 car dealerships.
He even stole cars for a little while: “We had car theft prevention training,” Clark explained. “Car theft was a self-insured component of our business. So, we would train on how to prevent it, and the only way to test [the training] was to actually do it.”
Clark even had the opportunity to work for the Tennessee Department of Commerce and Insurance as director of business development. It was there that he caught the captive bug, learning the ins and outs of the space. That education—and a captive insurance designation to boot—ultimately led him to Gallagher, brokering in the captive space.
This background, and Clark’s understanding of the full cycle of insurance, gave him the insight and know-how to help the affordable housing client navigate its unique business model.
“When we were looking at the risk profile, we were originally looking at a master program related to its property insurance. But over the course of our review, and our learning and understanding of the business, we identified a more pressing issue,” he explained.
Due to the short-term, co-living nature of the rentals, insurers were hesitant to provide coverage. The issue of tenant liability also came into play: Who would be liable should a loss occur, and how would each individual tenant or property owner choose to insure?
Building a First-of-Its-Kind Captive
Within the client’s growing housing technology model, there could be thousands of tenants across the states at any given moment. Renters’ contracts could certainly be used to place insurance responsibility on a particular individual, but they might not always be defined fully.
“In the event of an actual claim or occurrence, we identified that these contracts—though they would direct obligation to an individual—those individuals would not be able to indemnify the other party,” Clark said. In essence, if a homeowner was renting out a space and the tenant were to cause damage, like a house fire, the question became, would the tenant have adequate coverage or would the homeowner be held responsible? One step further, how would the client’s insurance play into it as well?
Clark estimated there are more than 30,000 tenants within the program, which could become “incredibly difficult … to monitor compliance of every individual having their own insurance.” And a contract might only require that the tenants have insurance; that doesn’t necessarily mean they actually have acquired accurate coverage on their own.
“We recognized … given the nature of how this client operates that we needed to tailor or manuscript a policy in order to solve these potential gaps in the coverage,” Clark said.
Clark put his captives background to the test. In his words, he acted as the quarterback for the client, bringing in front-end carriers, MGAs, captive managers, actuaries, and more to discuss the potential of creating a first-of-its-kind captive to manage and maintain coverage for everyone involved.
It took dedication, presentations, education and “everything you could imagine required to build this business plan,” as Clark, Gallagher, and the client walked through the feasibility process.
Clark noted, “When you see one captive, you’ve seen one captive. Because every time you start to go down the path of creating a captive, you’re going to identify things that are specific to that client or that risk itself.”
This endeavor was no different. Questions on scale and growth came into play as the captive was molded around what the client needed to keep operations going.
“We started out with a simple tenant liability program. If a tenant causes a fire, there’s smoke damage, water damage, something of that nature, you’ve got your standard types of coverage. But what makes this different is that we created sublimits within the policy to help with eviction, to help with some third-party liability, to help with a loss of income,” explained Clark.
His efforts paid off, and not just for the client, the homeowners and their tenants; Clark’s work earned him a 2026 Captives Power Broker win.
A Blueprint for Long-Term Success
The ability to take something from idea to creation doesn’t happen overnight, something that Clark truly appreciates in his role as a broker. Patience is a key part of working through the challenges, education, and successes of creating any new type of risk mitigation plan.
According to Clark, every captive has a few components that must be worked through—both with the client and on the insurance side. “There’s various milestones. One being actuarial and understanding the math … there’s the regulatory component.”
He noted educating all necessary stakeholders to obtain buy-in as additional steps that must always be taken into account or addressed.
“Captives take time, and as a broker and as a captive consultant, it is a process that will have challenges along the way. It’s key to be patient, work through them … and then [it’s important] to be continually learning and challenging yourself along the way,” Clark said. &