

 Newsletters
 Risk Central
 Digital Edition
Nationwide’s John Anthony on Turning E&S Market Complexity Into Opportunity
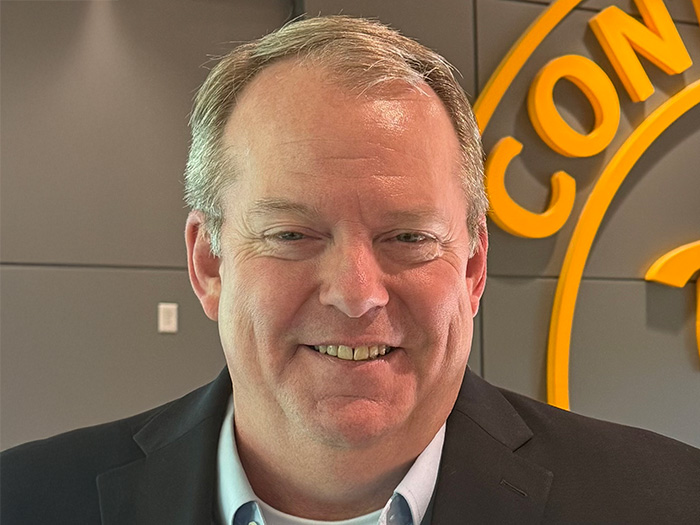
Risk & Insurance® Editor in Chief Dan Reynolds recently caught up with John Anthony, Sr. Vice President, Nationwide E&S Wholesale Contract P&C and Excess business. The following transcript was edited for length and clarity.
Risk & Insurance: Thanks for meeting with us, John. What factors are adding to the complexity in the placement of E&S risks?
John Anthony: The entirety of the insurance industry is becoming more sophisticated, especially on the standard lines side. That means the business flowing into the E&S marketplace is inherently going to become more complex. I think a lot of that gets compounded by shifting ideals in tort liability and regulatory reform, which really continue to change the risk landscape.
The good news is that the E&S marketplace is built to handle that level of complexity. The flexibility allows carriers and wholesale partners to respond to environmental, legal, and economic factors as they continue to evolve. We can oftentimes evolve at a pace that the standard lines companies can’t compete with.
R&I: How is the relationship between carriers and the wholesale brokerage community evolving?
JA: With the growing complexity within the marketplace, wholesale partners are looking for more than just capacity from their carriers. They want insights, sophistication, and practical guidance from their carrier relationships so that they have a better go-to-market access point.
That can really mean a bunch of different things. Help navigating new and emerging risk scenarios, sharing emerging trends, and identifying opportunities that may not be apparent on the surface. All of those things a carrier can help a wholesale partner with to really tackle this complex market environment.
R&I: What does disciplined underwriting mean, and how does it play into the carrier and distribution partner relationship when placing risks?
JA: Disciplined underwriting is a core tenet of any successful insurance carrier. The one thing we can count on, no matter what the market cycle is, is that it’s going to change. Anyone who has spent any substantial amount of time in the industry understands that underwriting discipline is what carries a company through the ebbs and flows of market cycles, allowing them to remain consistent, reliable stewards of their products and serve policyholders over the long term.
When capital comes into a marketplace that is less disciplined than core players, it creates a lot of uncertainty for everybody involved. Wholesalers and retailers often find themselves scrambling to find new homes for insureds when undisciplined entrants leave the market and don’t have the capacity to perform in perpetuity.
Consistent underwriting discipline gives our partners confidence that we, as a carrier, will stand behind the products we sell and allow a consistent approach year in and year out. It really strengthens that partnership between the carrier and the wholesale partner.
R&I: What are the long-term effects on carrier-distributor relationships when a carrier — whether disciplined or undisciplined — exits a market or relationship without proper signaling?
JA: It is absolutely a compounding factor. Our wholesale partners spend considerable time trying to find solutions in perpetuity for their insureds. When they have to go back to those insureds who have already found a home or solution and find them a new one while simultaneously solving for new opportunities, it creates significant churn within the marketplace.
What we’re really selling is a promise to our wholesale partners of consistent underwriting discipline. When that promise isn’t able to be upheld year in and year out, it creates considerable consternation.
Our wholesale partners have to explain to their retail partners why the new carrier will provide a more consistent approach than the last one. They have to communicate with their insureds, and it just creates substantial churn.
R&I: How is the increase in available data affecting underwriting decisions and response times?
JA: The data and insights that we as an industry are able to pull nowadays have really transformed the industry in a very short amount of time. Historically, even when I was growing up in the industry, underwriting was often considered an art. You relied upon your experience and your intuition to solve those complex risk problems.
Today, underwriters have so much more information at their fingertips to inform the way that they evaluate risk, make decisions, understand the impact of an individual decision on an entire portfolio, and really bring a lot of sophistication to that process. This provides a lot of consistency that addresses what we were talking about before regarding inconsistent product or market access. It’s also easier to share information and make relevant risk data available.
Instead of hunting and pecking for individual attributes, underwriters can be a lot more effective and efficient in their decision-making process. That easy access to data provides an efficient and effective underwriting process, translating into quicker turnaround times and more consistent solutions for our partners.
R&I: When a risk comes across your desk that you haven’t seen before or don’t have an existing solution for, how do you approach it as a specialty underwriter?
JA: This is really where it’s our time to shine as an E&S market, and specifically as a carrier that prides itself on its underwriting expertise and its flexibility to provide a solution. If a risk falls outside of our traditional transactional process or our traditional solution, underwriters can draw on all that expertise and then employ the use of those tools and resources to find the right combination of forms, terms, and conditions that satisfy an insured’s needs while still remaining within the appetite of the carrier.
One of the things that I like to think about is “No” as a last resort, and underwriters are charged with finding complex solutions to complex risk problems. This challenges underwriters to use their expertise to find a solution for all parties where appropriate and sustainable. It really differentiates us from a traditional market.
R&I: How do you characterize opportunities in the wholesale market, particularly regarding your relationship with the distribution network?
JA: I think the greatest opportunity exists when wholesale partners can clearly articulate the problem they’re trying to solve for their clients and carriers. It’s also incumbent on the carrier to listen to what those problems are. A carrier needs to have the ability to evolve in a way that aligns with how their partners want to transact differently.
Relying on that traditional go-to-market approach can cause both a carrier and a partner to stagnate within the market. But when carriers and partners can collaborate together and find new solutions for that ever-changing, complex marketplace we’ve been discussing, everybody within the transaction wins.
We see wholesale partners as an extension of our underwriting teams, our marketing teams, and our customer service capabilities. They’re the boots on the ground. They’re the ones that know their territories and have deep knowledge of their product and their clientele. When both sides really work to solve complex risk problems, everybody wins within that solution-oriented mindset.
R&I: Looking ahead, what should wholesale brokers be thinking about to achieve the best results with their specialty underwriting partners?
JA: I believe that many wholesalers are already thinking forward in the same way I’ve been discussing — with the sophistication needed to tackle this complex marketplace. Wholesalers that invest in great solutions, capabilities, and sophistication, and then pair with carrier partners that can match that sophistication and go-to-market strategy, are going to be very well positioned to succeed.
That means being able to drive market access and market share, evaluate and select risk very thoughtfully in this complex marketplace, and identify portfolio opportunities. But at the end of the day, the ability to execute wins.
When you bring all of those capabilities together and demonstrate that end-to-end underwriting expertise and sophistication in your go-to-market strategy, we can exist within any market. This is especially true when the market becomes more complex and drives additional opportunity to E&S carriers and wholesale partners.
R&I: Is there anything about this topic that we haven’t covered?
JA: I think this was very comprehensive and this is a great topic to be discussing. A lot of people see complexity as a threat where we should all be seeing it as an opportunity. There are carriers that wait in the background for something to happen. However, I think carriers and partners that are seeking alpha opportunities are really going to have an opportunity to shine. &