AI data centers and renewable energy investment alone could produce roughly $200 billion in cumulative commercial property and casualty premiums through 2030, according to Swiss Re Institute.
Lloyd’s of London generated a 22.0% return on capital in 2025, even as A.M. Best warns that softening market conditions could pressure results in the years ahead.
Global reinsurance capital climbed to $688 billion in H1 2026 even as premium volumes shrank, deepening a supply-demand imbalance, according to Gallagher Re.
The US P&C industry’s net underwriting gain nearly tripled in the first half of 2026, up from $11.6 billion in the first half of 2025, according to Verisk and the AAPCIA.
Rising exposure, demand surge and climate shifts are pushing the global insured average annual loss from natural catastrophes to $171 billion, according to Verisk.
Swiss Re report finds premium growth holding at 5% CAGR even as AI-driven threats and a widening protection gap push insurers to rethink coverage adequacy
The line has outperformed the broader property & casualty industry by more than 20 percentage points annually over the past four years, according to AM Best.
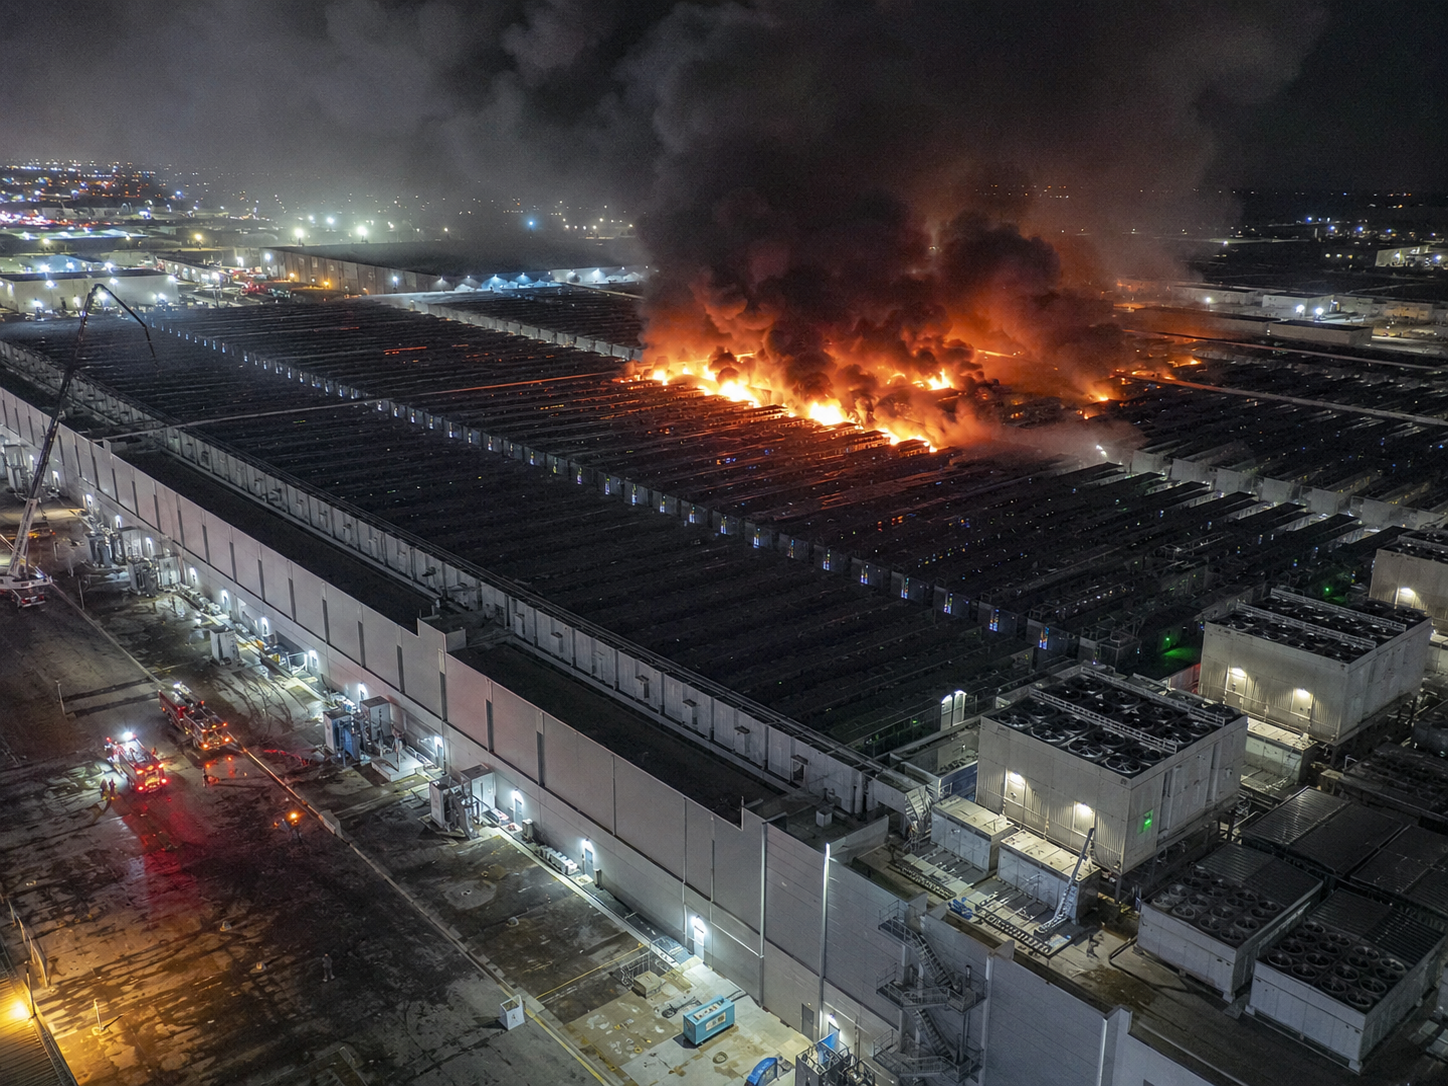
Fire drives the majority of insured data center losses even as natural catastrophe exposure, lithium-ion battery risk and construction complexity reshape the sector’s risk profile, according to Allianz Commercial.
Prices for primary directors’ and officers’ liability policies with the same limit and deductible rose 0.6% in the second quarter of 2026 compared with a year earlier, Aon reports.
The Baldwin Group’s Q2 Market Pulse ties the property downturn to falling reinsurance costs and a quiet hurricane outlook, even as litigation and tariffs keep casualty severity high.
Underwriting performance at AM Best-rated US captives continues to beat commercial casualty peers, generating an estimated $8.2 billion in savings for captive owners between 2021 and 2025.
As construction projects grow more complex and contractual requirements intensify, contractors are seeking efficient ways to meet their coverage obligations without sacrificing protection
AM Best maintains a stable outlook for the global cyber insurance segment, citing robust demand and favorable profitability even as premium growth slows and competition intensifies.
Total real premium growth will ease sharply from 2025’s cyclical peak even as insurers become more critical shock absorbers in a fracturing global economy, Swiss Re Institute found.
Abundant capacity and disciplined underwriting are giving buyers greater leverage over pricing and structure, though risk differentiation increasingly determines outcomes, according to Risk Placement Services.