

 Newsletters
 Risk Central
 Digital Edition
Fast Growing Industries Could Generate Up To $48 Trillion in Revenue, Reshaping Insurance
Eighteen fast-growing industries, from A.I. software and cybersecurity to electric vehicles, space and obesity drugs, are poised to reshape the risks that insurers underwrite and could become a source of new business as rate-driven premium growth slows, according to a report from McKinsey’s Financial Services Practice.
The report builds on McKinsey Global Institute research identifying these emerging “arenas,” which could generate $29 trillion to $48 trillion in revenues by 2040 and drive up to one-third of global growth. The arenas grew about 10 times faster than other industries between 2022 and 2025, adding roughly $18 trillion in market capitalization, with A.I. alone accounting for $11 trillion of those gains.
The shift comes as insurers face slowing premium growth after years of expansion driven largely by rate increases rather than new coverage, McKinsey said.
Life Insurers Face a Rewrite of Mortality Assumptions
McKinsey said GLP-1 obesity drugs and biotechnology advances such as genomic testing are poised to reshape the disease-burden assumptions underlying life, disability and annuities pricing.
Trial data cited in the report show GLP-1 drugs can reduce major cardiovascular events by 20%, and Munich Re’s analysis of 41 million insured U.S. lives estimated additional annual mortality improvement of 0.2% to 0.5% for about 20 years, according to the report. That means policies priced on pre-GLP-1 assumptions “may systematically overprice treated populations,” McKinsey said.
Swiss Re, cited in the report, noted that GLP-1-driven increases in lifespan could extend pension payout periods, requiring annuity and pension providers to reassess longevity assumptions. Separately, McKinsey said genomic data is pushing life insurance away from pooled risk models toward individualized mortality and morbidity assessments, raising ethical and regulatory questions about the use of genetic information in underwriting.
Personal Auto and Home Coverage Confront New Severity Risks
For personal lines, McKinsey pointed to electric vehicles (EVs), shared autonomous vehicles, drones, embedded e-commerce insurance and cybersecurity as the arenas most likely to disrupt home and auto coverage.
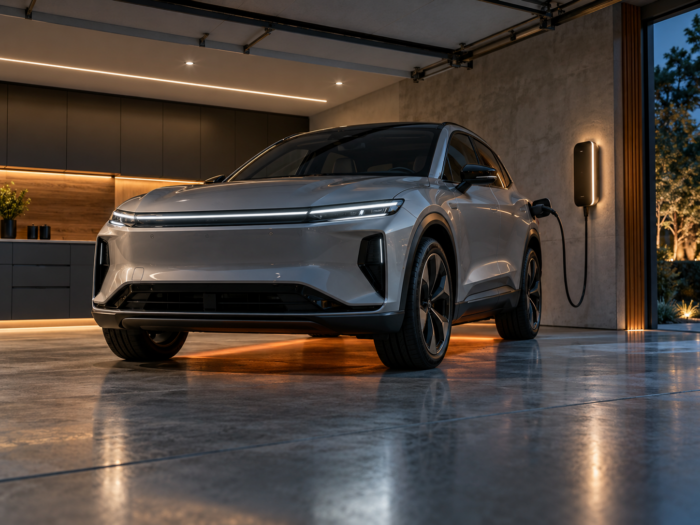
EV repairs cost 20% to 30% more than for internal combustion vehicles, according to Association of British Insurers data cited in the report, and battery damage frequently triggers total-loss write-offs rather than repairs. Thermal runaway from vehicle batteries also introduces fire risk that crosses from auto into homeowners’ coverage, particularly in home garages, McKinsey said.
As shared autonomous vehicles expand, McKinsey projected that about $5 billion in annual U.S. premiums will shift from personal to commercial auto insurance by 2030, while $140 billion to $160 billion of the personal mobility insurance market will be disrupted by connected, shared and autonomous vehicles. Liability in that scenario moves from individual drivers to platforms, automakers and technology providers, the report said.
Commercial Carriers Confront Concentrated, Systemic Exposures
McKinsey identified six arenas already significant to commercial insurance: cybersecurity, data centers and cloud services, space, semiconductors, robotics and future air mobility.
Cyber risk has evolved into what McKinsey described as a dynamic threat environment in which a single software vulnerability can trigger simultaneous claims across thousands of policyholders, more like a natural catastrophe than traditional liability. Beazley has issued $670 million in cyber catastrophe bonds and more than $1 billion in cyber excess-of-loss cover, according to the report.
Hyperscale data centers now carry total insured values above $10 billion, McKinsey said, citing S&P Global, prompting Marsh to launch Nimbus, a dedicated insurance facility for large-scale data center construction.
In space, the number of active satellites has grown from about 2,000 in 2019 to more than 18,000 today, the report said, while roughly 90% of advanced semiconductor chips come from facilities concentrated in Taiwan, creating global contingent business interruption risk from a single disruption.
Across all lines, McKinsey said A.I. is also reshaping insurers’ own operating models, with Chinese insurer Ping An automating nearly 60% of accident and health claims and Zurich using an A.I.-supported fraud-scoring tool across more than 600,000 annual non-life claims.
Obtain the full report here. &