

 Newsletters
 Risk Central
 Digital Edition
AmTrust’s Kevin Sullivan on Why Underwriting Discipline Will Define the 2027 Property Market
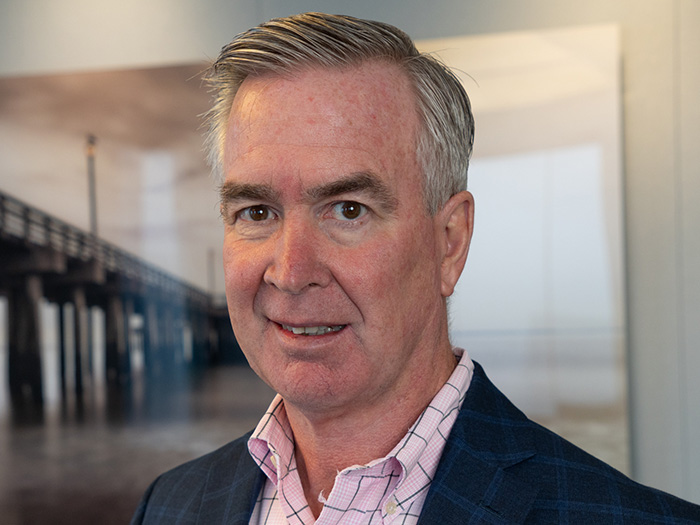
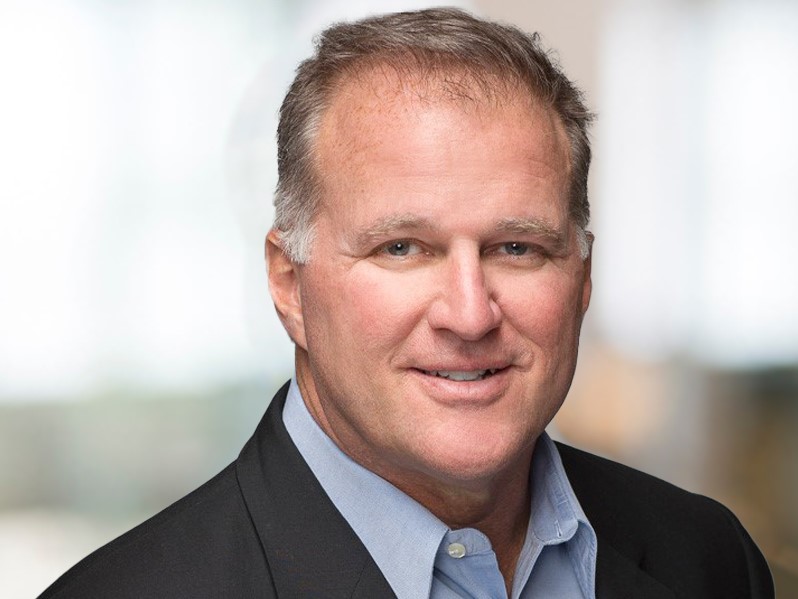
Risk & Insurance® recently caught up with Kevin Sullivan, Head of Property Reinsurance | East Re Insurance, LLC, an AmTrust Company. What follows is a transcript of that discussion, edited for length and clarity.
Risk & Insurance: Thanks for your time, Kevin. As you look ahead to 2027, how would you characterize the current state of the E&S property market, and where do you see it heading over the next year?
Kevin Sullivan: Year to date we are seeing property rates fall more than originally expected, with decreases of over 30% in some areas and significant competitive pressure on more generic property business. We expect these decreases to moderate, though that remains to be seen.
As we think about 2027, the biggest strategic challenge for carriers will be maintaining underwriting discipline when premium growth becomes harder to achieve through rate increases alone. The market will remain well capitalized and highly competitive, but the easy gains from the hard market are behind us. Capacity is abundant, pricing pressure continues to increase, and the carriers that succeed will be those that maintain underwriting discipline, deploy capacity selectively, and resist the temptation to trade margin for growth.
R&I: What factors do you expect will have the greatest influence on E&S property market conditions in 2027?
KS: The record level of capacity will continue to play a major role in the market. With the abundance of capital, low cat activity, continued strong property results, and underwriters having pressure to grow, I would expect continued rate softening, albeit not as much as we’ve seen in 2025 and 2026, but still a buyer-friendly market.
R&I: Where do you see the greatest opportunities emerging within the E&S property market, both for carriers and the clients they serve?
KS: From a carrier perspective, underwriters need to expand their knowledge and not just focus on commodity risks that are more price driven. The best priced risks are those that are likely found on the complex side, where underwriting skill matters more than simply having capacity. Being that the market is still not at the bottom, clients (buyers) should continue to look for broader coverage, reduced rates, and lower deductibles.
R&I: What challenges or areas of uncertainty do you believe the E&S property market will need to navigate in the year ahead?
KS: Due to the amount of capital in the market, it will continue to be competitive. Rates will continue to decline as more pressure gets put on terms and conditions. Brokers will seek broader forms, higher limits, lower deductibles, and less restrictive warranties.
The industry made great strides between 2022 and 2024, so we don’t want to give that back with undisciplined underwriting. The market is heading into a period where underwriting discipline, portfolio management, and risk selection will matter more than capacity deployment. Those who maintain discipline through the soft market will be best positioned when the cycle inevitably turns again.
R&I: Turning to property reinsurance, how do you expect that market to evolve in 2027, and what developments will you be watching most closely?
KS: The property reinsurance market is extremely well capitalized, alternative capital remains abundant, property cat pricing is still viewed as adequate, and capacity is expanding and not contracting.
In 2027, we anticipate further pricing declines, but the question is to what degree? We expect capacity to remain readily available. Many insurers are going from defense to offense due to the softening pricing environment, so we could see more buying.
During the hard market, most reinsurers focused on primary pricing discipline and improved reinsurance terms. Due to less margins in most treaties, I would also expect greater differentiation based on cat management, historical performance, portfolio composition, and data sophistication.
Companies that have these characteristics will likely attract more favorable treatment than average portfolios. That being said, one major hurricane or a series of events could alter the market. Property reinsurance will remain buyer-friendly, but at a more moderate pace than what we’ve seen.
R&I: What factors do you expect will have the greatest impact on property reinsurance pricing, capacity and terms as the market moves into 2027?
KS: The biggest driver will be CAT losses from now until the end of the year. Reinsurers are not capital constrained. Therefore, a typical CAT year is unlikely to change the downward market direction. However, several large events could change things and alter market conditions. Absent a major event, we’ll most likely see an increase in aggregate covers, lower attachment points, broader occurrence limits, and more favorable reinstatement provisions.
R&I: Where do you see the greatest opportunities and challenges emerging in the property reinsurance market as we head into 2027?
KS: The opportunity in 2027 is identifying and supporting underwriting experts who can produce sustainable returns despite the soft market conditions. These experts should know where we are in the market cycle, maintain discipline despite competitive pressures, develop superior analytics, expand through structured solutions rather than pure rate competition, and preserve underwriting and contract discipline while others chase market share. The biggest challenge will be reinsurers chasing premium by undercutting the market on price, terms, and conditions simply to gain market share.
R&I: How are conditions in the property reinsurance market influencing — or likely to influence — capacity, pricing and underwriting decisions in the E&S property market?
KS: During the hard market of 2022-2024, carriers were largely reacting to shrinking reinsurance capacity and sharply rising treaty costs. Today, the pendulum has swung the other way. Capital is abundant, competition has increased, and reinsurers are more willing to support growth. As a result, reinsurance is increasingly influencing E&S carriers to write more business, deploy larger limits, and compete more aggressively.
R&I: What should brokers and risk managers be thinking about now as they prepare for the property market conditions you anticipate in 2027?
KS: Brokers should be thinking about locking in structural improvements, not just premium reductions for their clients. The smart approach is to broaden policy wording, raise sub-limits, reduce cat and AOP deductibles, and provide less restrictive occurrence definitions. Rate reductions can disappear after the next major cycle. Improved coverage terms often remain in place much longer.
Risk managers should consider improving data quality. When underwriting tightens, carriers increasingly differentiate based on data quality rather than account size. Improved wildfire mitigation, flood protection measures, and business continuity planning are just a few ways managers can set themselves apart from the competition. For 2027, the conversation should be less about “how much lower can rates go,” and more about how we use today’s buyer-friendly conditions to prepare for the next disruption. &