

 Newsletters
 Risk Central
 Digital Edition
8 Questions on Technology, AI and the Agent Experience for Brent Skiles of Philadelphia Insurance
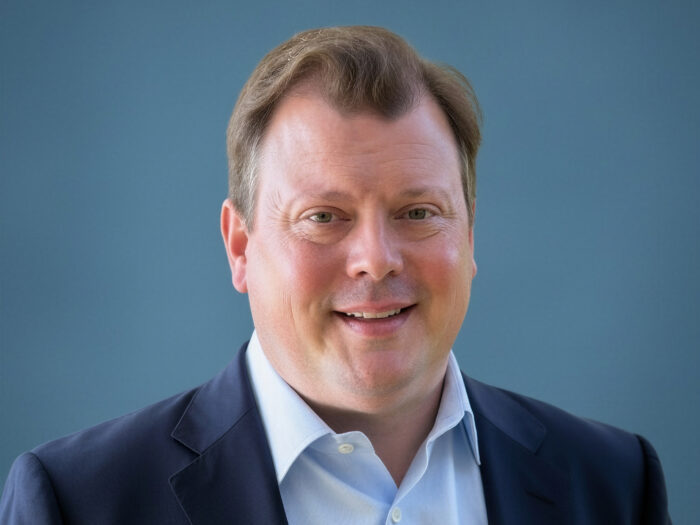
In August, Dan Reynolds, the editor in chief of Risk & Insurance, caught up with Brent Skiles, SVP & Chief Transformation Officer, Philadelphia Insurance Companies. What follows is a transcript of that discussion, edited for length and clarity.
Risk & Insurance: Thanks for meeting with us Brent. What are agents looking for when it comes to ease of doing business with a carrier?
Brent Skiles: What I tend to find is that agents are looking for speed, simplicity, transparency, and consistency.
They’re looking for carriers that are not just trying to automate everything or take the relationship out of the transaction. They are looking for ways to remove friction and simplify things. That means fewer handoffs and less time chasing information.
I think they want predictability as well. They want to understand and see consistent appetite being demonstrated and what information is needed from the insured. They want to have insight into how long things are going to take and who’s going to own the next step.
R&I: How are agencies and brokerages feeling about the quality of their interactions with carriers these days?
BS: I am seeing a little bit of variation out there. As some agents and brokers have put a lot of effort behind their technology evolution, I think that’s creating some additional friction. Either they’re ahead of the carrier that they want to do business with, or the carrier’s ahead and the dynamic lacks alignment.
But there’s a large pocket of agents, especially independent agents across the country, that are also looking for that personal connection. We do a lot of specialty business and a lot of niche business, and those agents are looking for carriers that they can still talk to on the phone. They want to bring that expertise to their clients, and I think they’re seeing some friction. The friction is in the way carriers are looking to perhaps streamline things so much that they’re missing the opportunity to help the agent best serve the insured.
I think we’re at an inflection point where we’re trying to work out this significant enhancement in technology that’s available to all of us, but still trying to apply that to what I think is a heavily relationship-based business. That’s a challenge.
We want to source that feedback. It is challenging because everybody is so fixated on wanting to move the technology forward that sometimes they forget that this is a relationship-based business. I think that is something that’s going to be critical to the way forward.
R&I: You mentioned that agents are looking for speed, simplicity, transparency and consistency. How is Philadelphia Insurance Companies approaching these needs?
BS: I think for PHLY, we have learned that speed is not just faster. There’s a lot of ways to do things faster. And I would say early on, we worked through some challenges around where we thought driving at pure speed would be the value that our agents and brokers were looking for.
It sounds so obvious, but it has to be a fast meaningful response.
We needed to focus on a rapid internal referral process and clear understanding of our appetite and decisions. Sometimes a fast “no” is much better than a slow maybe. We want everything to be faster, but that might not bring enough value or solve the problem.
In terms of simplicity, I think a lot of it is making the effort first to better utilize all the data that we have as a carrier that we can access through third parties and second to streamline what we’re asking our agents, brokers and insureds for.
Around transparency, the simplest way is we really don’t want our agents and brokers to have to ask where something is or ask why something happened. We want to make sure that we’re making things like the status of a claim, a submission, a billing issue, whatever they need from us that it is easy for them to understand where that sits.
The other piece of transparency is appetite and being consistent and clear in the way we communicate about it. What we’ve found is there’s a level of unique skill sets that are required to underwrite, handle claims or solve for a variety of different businesses out in the insurance market. But we don’t want the broker to have a different experience just because they’re working with a different division within our company.
That plays into consistency. We know we’re going to need that specialized judgment and human intervention, but we want the system to give them a consistent experience. So whether they’re working with us on a nonprofit or a sports camp, there’s uniqueness to each of those risks—but we want the broker to have a consistent experience. I think that helps create the efficiency that these agents need to run their businesses effectively.
R&I: Beyond getting to a quick “no,” how important is it to provide clarity and transparency around why an account is being declined?
BS: Resources for the carrier and for our agents can be tied up causing frustration.
If we can provide agents with information, they can better understand PHLY and thereby send potential accounts and submissions to us that have a higher likelihood of being placed. That’s more efficient for us and more efficient for them.
Technology is starting to make that easier because agents can now capture that information integrated into their submission process as they’re making potential carrier selections.
R&I: How does Philadelphia Insurance Companies balance serving agencies that prefer a tech-forward approach versus those that still want traditional phone conversations and personal relationships?
BS: It’s not all that well defined. There are some agencies that are driving a very tech-forward approach, and they’re looking for digital interaction models. They’re looking to have a very streamlined interaction.
But what they’re also telling us is, “Yep, we want that. We want to get out of the data entry business. We don’t want to enter things into your portal. We want to do an API integration. We want to give you the 50, 60, 70 pieces of information we have. You supplement it with anything you want. If you need a couple more things, if you’re interested, we’ll give it to you.”
They want that, but they also want the ability to call somebody. And that’s where I think we’re trying to build that balance—even the most tech-forward agents still want a relationship. Because we might be a small piece of a very critical large account for them, and they may need us to know that. And sometimes these digital interactions don’t really allow for that.
Then there are agents that are using some technology but are still taking a real people-first approach. So we’re also trying to maintain the ability for them to operate that way, whether they haven’t made all of the advancements yet in technology that they want or not. We want to be able to receive those submissions whether it’s a traditional email with a PDF attached or through a portal entry. We’re trying to offer those things as well.
R&I: How are the Philadelphia Insurance Companies using A.I.?
BS: We’re actively deploying multiple different A.I. solutions, and there are a lot of different variations of the way A.I. can be utilized.
Rather than simply an efficiency play or trying to use it to just make things faster, we really are trying to figure out how we can take all of this specialized and niche knowledge that we have—all of these underwriters and folks who have these relationships—and get them to use A.I., especially things like agentic A.I., to supplement and support them to really accelerate their decision-making.
We want to help them make better risk decisions by surfacing things like insights from our portfolio or characteristics of the risk or patterns that, again, might take a very long time even for a seasoned underwriter to figure out. We can use the tech to surface that stuff up for them, and they can then use their knowledge of the particular line of business or risk or product, but also their relationships, to be able to negotiate a best-case scenario outcome.
We’re also using A.I. to automate some things and especially deliver office efficiencies. We want to be able to have agentic A.I. plays that can help solve for things that traditionally we might have used Business Process Outsourcing or robotic process automation to solve for. So whether it’s an outsourcing play or robotics automation play, agentic is really coming in and replacing a lot of that work to drive more efficiency for the organization and free up our folks to be able to focus on the things that matter most.
R&I: What else should agents and brokers know about how Philadelphia Insurance Companies approaches developing relationships with the distribution part of our business?
BS: I think what we’ve been able to do really well is take a very deliberate approach. It sounds simple, but we try to make sure that we’re listening to our agents and insureds. We try to confirm that we’re understanding what they’re saying.
We take some action. We measure it. We go back, and we ask that question again. And we do that through a lot of formats.
We do that through our Voice of the Customer work and as we monitor and manage our Net Promoter Score. We also look very closely at our claims handling, of which PHLY has a 96.7% claims overall satisfaction rating. This helps to increase our broker partners’ confidence in the product that PHLY is delivering to our customers.
We also do that with a lot of agent panels. What we found is they really wanted certainty. And we wouldn’t have known that if we didn’t ask.
We have this group of agents and brokers who are really good partners of PHLY. They’re very transparent with us, and we iterate solutions with them. When they came back, they really wanted certainty. And what we found was – we were trying to make our existing process faster, and what they really wanted was for us to reengineer our process.
Once we did things like giving them an answer, giving them that “fast no” with insight earlier, that was way better than trying to reengineer the entire process to be faster. We just needed to reorder it. And it sounds so simple, but when you’re sitting in the bubble of your insurance company, you don’t always recognize that. &