

 Newsletters
 Risk Central
 Digital Edition
Sponsored Content by Sompo
Private Equity’s Reset is Reshaping Insurance
Private equity has spent the better part of the last few years in a holding pattern. Deal activity trailed historical norms, interest rates weighed heavily on financing decisions, and economic and political uncertainty made it difficult for sponsors and their investors to project what comes next.
For the insurance industry, this pause represented considerable opportunity. Brokers and carriers have used this period to build specialization, deepen relationships, and hone their processes to be best positioned as deal activity continues to normalize.
“Despite recent upticks in deal activity, an abundance of dry powder remains. Sponsors are approaching investments with far greater discipline around valuation, growth assumptions, and operational risk,” said Dan Reinert, SVP, Private Equity Practice Leader at Sompo. “What we’re seeing are firms running a more structured diligence process, with a clearer view of what truly drives value.”
Patient Capital, Selective Investing
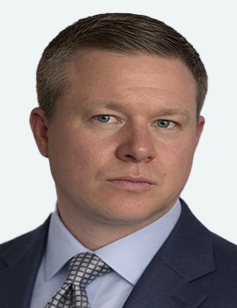
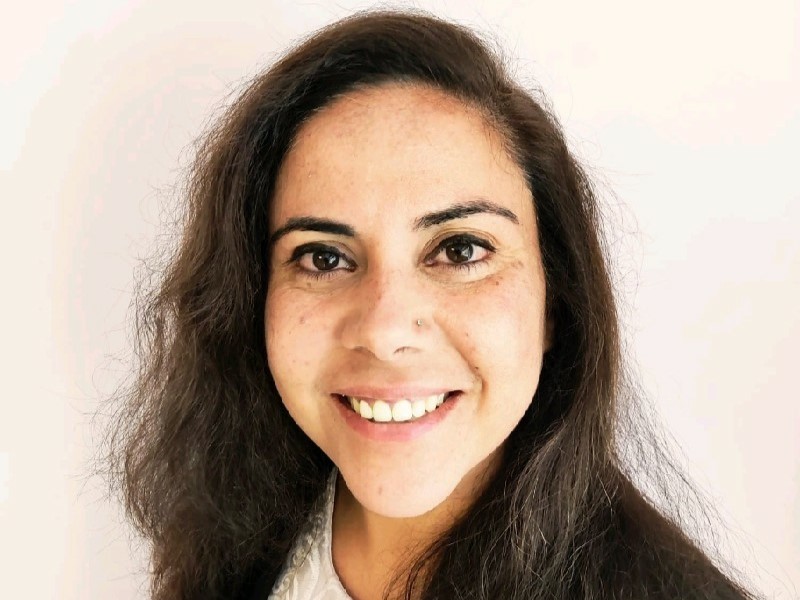
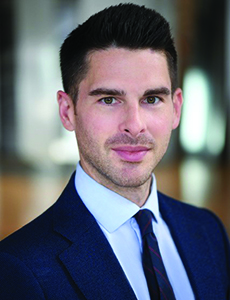
Dan Reinert, SVP, Private Equity Practice Leader, Sompo
The dominant theme in private equity investing today, according to Reinert, is patient capital. Firms are being highly selective on both the buy and sell side. While add-on and bolt-on acquisitions have continued largely uninterrupted, the broader deal environment has been muted, and sponsors are balancing new investments with the pressing need to generate exits and return capital to investors.
Interest rates sit at the center of this dynamic. “The cost and availability of capital remain among the most important determinants of private equity deal activity,” Reinert said.
“When financing becomes more expensive, the economics change quickly. As borrowing costs normalize and lenders become more active, sponsors gain flexibility to pursue acquisitions and exit opportunities.” Equally as important, he noted, is the alignment of expectations between buyers and sellers. “Sellers naturally want to maximize returns, and buyers don’t want to overpay. So as that valuation gap closes, that’s when transaction activity will accelerate more meaningfully.”
Beyond financing conditions, sponsors continue to navigate a complex backdrop of economic, political, and geopolitical uncertainty. Reinert emphasized that while each of these factors can influence investment decisions independently, together they shape confidence, capital deployment, and transaction timing.
“As market conditions stabilize globally, many of these variables begin to align and reinforce one another,” he said. “Greater certainty drives investor confidence and that tends to translate into increased transaction flow.”
The result is a market where liquidity remains front of mind, diligence is more rigorous than ever, and value creation, rather than financial engineering alone, has taken center stage.
A New Model for Serving Private Equity
The pause in deal flow has not slowed the transformation of how insurance is delivered to private equity clients. If anything, it has accelerated it. Brokerage M&A activity has been robust, with firms specifically seeking out targets that bring private equity expertise or operate in an M&A-oriented model.
“Private equity sponsors increasingly expect brokers to deliver integrated solutions across diligence, transaction execution, portfolio operations, and claims advocacy. That expectation has fueled consolidation across the insurance brokerage industry as firms seek to expand both scale and specialization,” Reinert said.
But scale and specialization alone are no longer enough. “A broad market footprint still matters from an insurance broker perspective, but private equity sponsors are now prioritizing platforms that can translate that footprint into durable earnings and operational leverage,” he said. “The most effective private equity-backed platforms pair M&A expertise with deep capabilities across property & casualty, financial & specialty lines, human capital and global risk management.”
What truly differentiates a brokerage firm, in Reinert’s view, is the ability to organize around private equity and operate cohesively across a sponsor’s portfolio — diligence through post-close and throughout the life of an investment.
Carriers, too, are recalibrating. Historically many carrier relationships were transaction-specific and centered around particular coverage or product needs. Today, carriers are increasingly evaluating opportunities through the broader lens of a sponsor relationship, and the recurring insurance spend represented across an entire portfolio.
“The carriers that are best positioned to succeed have been investing in people, process, and technology well ahead of the market coming fully back online,” Reinert said. “That means adapting to an evolving brokerage model, improving project response times, and building out supporting infrastructure required to operate with speed and efficiency in this space.”
That preparation extends to how sponsors themselves are managing risk. Reinert has observed a significant shift in the emergence of dedicated risk management functions within private equity firms, a concept that was virtually unheard of not long ago.
“Until recently, insurance was managed on a more decentralized basis, largely through deal teams or at the individual portfolio company level,” he said. “Today, we’re seeing more sponsors taking an active role and a more proactive approach. They recognize that effective risk management can protect enterprise value, improve operational performance, and help preserve investment returns.”
Insurance, once viewed primarily as a purchasing exercise, is increasingly being treated as a strategic business function.
Preparation as a Competitive Advantage
Serving private equity effectively requires more than transactional expertise. It requires understanding that private equity is a full-fledged operating model that demands deep industry knowledge and a holistic view across a sponsor’s entire portfolio.
“At Sompo, we view preparation as a competitive advantage,” Reinert said. “We’ve spent the last two years scaling a dedicated private equity practice, focused on greater responsiveness, portfolio-level visibility, and coordination across lines of business.”
Looking ahead, Reinert is confident that activity will continue to strengthen within a healthier, more stable private equity landscape, as financing conditions improve and valuation expectations converge between buyers and sellers. “Investors now expect greater clarity, stronger fundamentals, and a clear road map before committing capital,” he said. “That discipline creates an opportunity for insurance firms that have invested in specialization, technology, and talent to stand apart and capture market share.”
To learn more, visit www.sompo-intl.com

This article was produced by the R&I Brand Studio, a unit of the advertising department of Risk & Insurance, in collaboration with Sompo. The editorial staff of Risk & Insurance had no role in its preparation.