

 Newsletters
 Risk Central
 Digital Edition
Sponsored Content by Sentry
How Businesses Can Address Mounting Workforce Pressures Before They Turn Into Losses
Business leaders are navigating a challenging operating environment; and that may be an understatement. Supply chain disruptions, tariffs, labor shortages, and rising business insurance costs are no longer isolated concerns. They’re hitting companies simultaneously, creating workforce pressures that can quickly cascade into operational and financial losses.
According to Sentry’s 2026 C-Suite Stress Index: Midyear Report, 62% of surveyed leaders cite supply chain and logistics disruptions as a top threat. But close behind are economic pressures (53%, up from 44% earlier this year), tariffs and trade uncertainties (52%), and labor shortages (49%). The real story isn’t any single pressure; it’s the cumulative weight of all of them landing at once.
“C-suite leaders are under pressure to increase productivity, manage costs, and maintain operations,” said Jeff Cole, AVP of National Accounts at Sentry.
“What we’re seeing is a lot more uncertainty in the business marketplace. It’s really the culmination of all of those things at the same time that’s creating a lot of workforce pressure.”
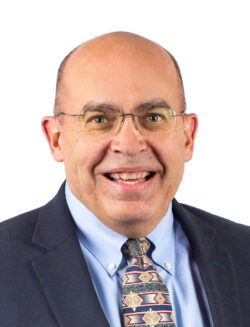
Jeff Cole, Assistant Vice President of National Accounts, Sentry® Insurance
A Macroeconomic Storm With Outsized Impact on Smaller Businesses
While the pressures affect businesses of all sizes, Cole noted that smaller companies tend to feel them more acutely. According to the Midyear Report, 68% of smaller employers—those with 10 to 49 employees—cite supply chain logistics as a concern, and 51% point to labor shortages, slightly higher than the overall average.
“In larger companies, if you’re missing a worker or two out of 200, that’s a little bit easier to make up,” Cole said.
“But when you’re a smaller company and you only have eight or nine workers and you’re missing one or two because you can’t find a replacement, that’s a large portion of your workforce. It puts a lot of pressure on the remaining workers and on the business to maintain the quality, to maintain the ability to produce products and services at the same standard in the same timeframe.”
Labor shortages, Cole said, are especially important in the workforce pressure conversation because of how they intensify operational trade-offs. When workers are scarce, leaders often lean on overtime, faster production schedules, delayed training, and fewer breaks. Over time, those decisions ripple through safety, quality, retention, claims—and even business continuity.
When Pressures Translate Into Losses
The downstream effects of unaddressed workforce pressures extend far beyond workplace injuries. According to the Midyear Report, 49% of executives report more errors or lower-quality work, 48% report decreased employee satisfaction, and 32% report increased employee injuries or close calls.
“The immediate reaction is that we’re going to see losses,” Cole said.
“But it goes well beyond that. It’s lower quality work. It’s the amount of rework because people are rushing through. It’s the number of customer complaints. It’s turnover because your workers are getting frustrated. It’s lost time because machines are breaking down, you’re pushing them too hard. It’s things like auto accidents because people are rushing to get something to a customer on time.”
These signals, Cole said, build on one another. Decreased employee satisfaction makes it harder not only to retain workers but also to recruit new ones. Lower-quality output damages customer relationships and brand reputation. And once injuries and close calls begin climbing, the pressures have already been compounding for some time.
“It’s like a boulder rolling down the hill. It just keeps gaining speed, gaining momentum,” Cole said. “They (survey respondents) point to broad risks across safety, quality, productivity, retention, claims; the totality of what’s going on in that business.”
Building a Practical Framework to Identify and Act on Risk
Addressing workforce pressures before they turn into claims requires a practical, repeatable risk management framework. Cole outlined five components: identification, assessment, escalation, action, and monitoring.
Identification starts with pulling data and observations from across the business—safety, claims, HR, operations, quality, finance, and legal. Leading indicators include overtime levels, missed breaks, near misses, production schedule changes, training delays, maintenance delays, difficulty attracting talent, and supervisor span of control.
“All those are looking from a different lens at the same issues, which is the workforce pressures that exist,” Cole said.
Assessment involves understanding how those pressures may affect the broader business. Claims data is valuable for a deep dive, but the real goal is to spot risks before claims occur. Escalation is the prioritization process and requires setting thresholds in advance. Not every risk can be addressed at once, so leaders need to focus resources on the pressures creating the biggest exposure. For example, flagging a 10% drop in workforce availability or three near misses in a month as triggers that warrant executive attention. And, sometimes, actual claims occur and you need to understand those as well. Tenure-based metrics have become especially important, Cole noted, given today’s labor environment.
“There are a lot of people entering the workforce now, and we’ve seen an uptick in claims from those new to the workforce. Maybe they were rushed through training. Maybe they didn’t get appropriate training at all. Looking at tenure-based metrics is a critical element of understanding your workforce and understanding where your biggest risks might be.”
Once you’ve prioritized, you need to take action. That may come in the form of more training, better safety, or newer machines, to name a few. Monitoring closes the loop. That means measuring whether the actions taken are reducing risk and adjusting course if they aren’t.
Collaboration Across Agents, Risk Managers, and Carriers
For smaller businesses that don’t have dedicated risk managers, agents and brokers play a critical role in guiding this process. Cole emphasized that the agent or broker doesn’t need to own the entire framework; but they can help facilitate the collaboration between risk managers and insurance providers.
Agents and brokers can raise workforce pressures at renewal or prospecting conversations, flag significant business changes, and connect insurance, claims, safety, and operational discussions. Risk managers can integrate internal signals from HR, claims, operations, quality, finance, and legal into a unified view. And insurance providers can bring broader perspective, drawing on patterns observed across similar businesses.
“Sometimes the best lessons learned are those learned by other people,” Cole said.
“As we look across our book of business at similar types of businesses, what have we observed there? What have been challenges that those businesses have had? We can help use that information to prevent those same types of accidents from happening at another company.”
That collaborative, data-informed approach is what allows business leaders to anticipate pressures rather than react to them.
“It’s really a matter of working together with the perspective that whether you’re the agent, the risk manager, or the insurance provider, it’s all about collaboration,” Cole said. “Helping the leaders see those workforce pressures before they turn into claims is always what we intend to do. That’s definitely a better way than just analyzing claims after they occur.
To learn more, visit https://www.sentry.com.

This article was produced by the R&I Brand Studio, a unit of the advertising department of Risk & Insurance, in collaboration with Sentry. The editorial staff of Risk & Insurance had no role in its preparation.